What Stablecoins Change in Payment Infrastructure
A practical map of issuance, reserves, redemption, blockchain settlement, custody, compliance, FX, interoperability, and the risks hidden by a stable price.
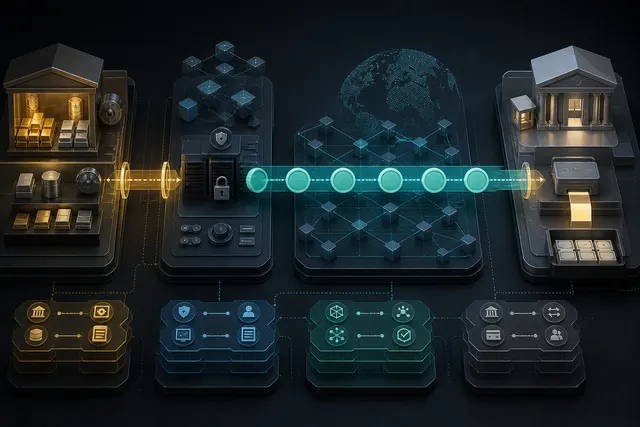
A stablecoin can move a token between blockchain addresses without waiting for a bank transfer to cross every institution in the traditional payment chain. That does not mean the complete payment has settled, that the recipient holds bank money, or that one token is economically interchangeable with another.
The token transfer is one layer in an arrangement that may include an issuer, reserve custodian, banks, smart contracts, validators, wallets, exchanges, liquidity providers, compliance services, foreign-exchange providers, and local payout rails. Evaluating stablecoins as payment infrastructure requires tracing value and obligations across all of those layers.
This article explains the architecture and risks. It does not recommend a token, issuer, wallet, exchange, or investment.
“Stablecoin” describes a target, not a guarantee
Stablecoins use different mechanisms to target a reference value. Some are issued against off-chain reserve assets and promise redemption. Others are overcollateralized with on-chain assets, use hedging positions, or depend on algorithmic incentives. These designs create different claims, failure modes, and legal relationships.
For a fiat-referenced, reserve-backed arrangement, ask four separate questions:
- What legal claim does the holder have, against whom, and under which terms?
- What assets support that claim, where are they held, and with what liquidity and credit risk?
- Who can redeem directly, at what minimum, fee, time, and identity requirement?
- How does a secondary-market holder convert the token into usable local money?
A market price near the reference value answers none of these completely. It reflects current trading and arbitrage conditions, which can change when redemption, banking, liquidity, or confidence is stressed.
Follow the payment from beginning to end
Consider a business that wants to pay a supplier in another country. A simplified path can contain these stages:
- The payer obtains tokens through an issuer, exchange, broker, or existing balance.
- A wallet constructs and signs a blockchain transaction.
- The network accepts, orders, and confirms the transaction under its own rules.
- The recipient or its service provider recognizes the incoming token.
- The recipient holds it, swaps it, or submits it through an off-ramp.
- An issuer or intermediary redeems or sells it and obtains bank money.
- Foreign exchange and a domestic payment rail deliver the requested local currency.
- Both businesses reconcile fees, exchange rates, timing, invoices, and accounting records.
Only the middle of this sequence is the on-chain transfer. The CPMI analysis of stablecoins in cross-border payments emphasizes denomination, on- and off-ramps, coexistence with other payment methods, regulatory differences, and central-bank functions. A faster token leg cannot remove the slowest or least reliable external dependency.
Issuance and redemption anchor the arrangement
In a simple reserve-backed model, an authorized customer sends funds to the issuer or its banking partner, and the issuer mints a corresponding quantity of tokens. For redemption, tokens are returned or burned and funds are sent through the banking system. Secondary holders may never interact directly with the issuer; they trade through intermediaries whose price, fees, limits, and availability can diverge from direct redemption.
Issuer documentation is a claim that must be read with its terms. Circle’s technical overview of USDC, for example, describes issuance on multiple blockchains, redemption, and monthly reserve attestations. That information is useful for understanding the stated design, but an integration still needs the current legal terms, eligible customers, supported networks, contract addresses, transfer controls, fees, and jurisdiction-specific access.
Do not confuse an attestation with a complete audit of the whole arrangement. Determine its date, scope, measurement criteria, reporting entity, assets and liabilities covered, custodian confirmation, exceptions, and whether it addresses only a point in time. Reserve reporting does not by itself test cybersecurity, operational resilience, wallet controls, sanctions processes, smart contracts, or a holder’s legal priority in insolvency.
Reserve composition changes liquidity risk
Cash at a bank, short-term government obligations, secured lending, commercial paper, longer-duration securities, and other assets do not behave identically under stress. Relevant properties include credit quality, duration, market liquidity, concentration, custody, settlement time, encumbrance, and the currencies of assets and liabilities.
Even high-quality assets can create timing risk if redemptions are immediate while asset sales settle later. Bank deposits introduce exposure to banking partners and access windows. Segregation can reduce some risks, but its legal effect depends on account structure and applicable law.
Review reserve assets together with redemption demand, liquidity facilities, concentration limits, valuation, operational cutoffs, and contingency funding. “Fully backed” is not a complete liquidity model.
Blockchain confirmation is not the whole meaning of finality
A network can provide technical confirmation that a transaction was included and is increasingly difficult to reverse under its consensus rules. Payment finality also depends on legal rules, smart-contract behavior, chain reorganizations, validator or sequencer outages, bridge design, fraud or compliance interventions, and whether the recipient considers the asset acceptable discharge of an obligation.
Define operational finality for each supported network:
- required confirmation or finalization state;
- response to reorganizations, forks, or halted networks;
- handling of duplicate submissions and uncertain transactions;
- the canonical token contract and supported version;
- whether an issuer can freeze addresses, pause transfers, or upgrade a contract;
- how wrapped, bridged, or unofficial versions are rejected;
- when the business ledger marks an invoice paid.
Never rely on a ticker or token name. Verify chain identifier and contract address through a controlled registry. A token with a familiar display symbol can be an unrelated contract.
Multi-chain support fragments liquidity and operations
The “same” issuer token may exist natively on several networks. Balances are not automatically transferable between them. Moving value can require issuer mint-and-burn infrastructure, an exchange, a bridge, or market makers. Each route has distinct contracts, custody, fees, timing, limits, and failure recovery.
Bridged representations may create a claim on a bridge or custodian rather than directly on the original issuer. If the bridge is compromised or the wrapped token loses liquidity, the native reserve backing does not automatically repair the holder’s position.
Maintain an explicit allowlist of networks and native contracts. Reconcile total exposure by issuer and legal claim, not merely by chain. Test what happens when one network is congested, paused, reorganized, or removed from issuer support.
Custody becomes part of the payment service
Bank-account access can often be revoked or recovered through institutional processes. A blockchain payment may be irrecoverable if a signer authorizes the wrong payload or if key recovery fails. Hosted wallets shift some control to a service provider; self-custody shifts it to the organization or user. Neither label proves security.
Business payment systems need:
- separated request, review, approval, signing, broadcasting, and reconciliation duties;
- independent decoding of destination, network, contract, amount, fee, and method;
- address governance and strong controls for first-time beneficiaries;
- transaction, velocity, and exposure limits;
- tested key rotation, backup, recovery, and incident procedures;
- monitoring for policy changes, new devices, unusual routes, and failed approvals;
- an exit path from wallet, custody, exchange, and infrastructure providers.
Contract-level administrative powers and issuer controls also matter. A transfer can be valid under network consensus yet later frozen at the token contract or blocked at an off-ramp.
Compliance does not end at an address check
Public ledgers expose transaction histories, but addresses do not reliably identify their controllers. Screening tools combine incomplete attribution, heuristics, sanctions data, and risk rules. They can produce false positives, miss new activity, or disagree about indirect exposure.
FATF’s 2025 targeted update discusses issuer freezing and monitoring capabilities, intermediary roles, public-ledger analytics, attribution limits, and uneven global implementation. A payment operator still needs customer and beneficiary controls, sanctions and AML processes, escalation, evidence, privacy safeguards, and rules for blocked or mistaken transactions.
Define decisions before integrating a score: which events block, delay, or escalate; how evidence is reviewed; how a customer contests an error; what is retained; and which jurisdictions and counterparties are supported. Do not leak sensitive customer information into unnecessary analytics systems.
Cross-border movement does not eliminate foreign exchange
A token referenced to one currency exposes a recipient who needs another currency to exchange-rate and liquidity risk. The token may move continuously while banks, exchanges, or domestic payout systems operate on local schedules. Fees can appear in spread, network gas, priority, custody, withdrawal, redemption, FX, and domestic delivery.
Measure the complete quote and completion time from the payer’s starting asset to funds usable by the recipient. Record who bears price movement while a transaction is pending or disputed. A low blockchain fee can coexist with an expensive or unreliable final conversion.
Governance and risk span the full arrangement
The CPMI-IOSCO application of financial-market-infrastructure principles treats a stablecoin arrangement’s transfer function and interdependent activities as a system, not merely a token contract. The FSB’s high-level recommendations similarly address governance, risk management, data, recovery, redemption, stabilization, and cross-border coordination.
Implementation is not uniform. The FSB’s 2025 peer-review findings reported significant gaps and inconsistencies across jurisdictions. Therefore, a payment launch needs jurisdiction-specific legal and compliance review; a global technical API does not create global regulatory permission.
Map ownership and recovery for every critical function:
- reserve management and custody;
- issuance, redemption, and contract administration;
- blockchain and node access;
- wallet and key custody;
- compliance and analytics;
- exchange and liquidity provision;
- FX and local payout;
- customer support, disputes, and incident communication.
Identify correlated dependencies. Several vendors may rely on the same cloud, bank, node provider, identity platform, or blockchain sequencer.
Test the complete payment corridor
A pilot should use representative values and real operational boundaries while limiting financial exposure. Test:
- issuance and direct or indirect redemption under normal and stressed conditions;
- each approved network, contract, token decimal, and confirmation policy;
- chain congestion, fee spikes, reorganizations, outages, and duplicate submissions;
- wrong-network and unsupported-token deposits;
- wallet loss, signer unavailability, policy change, and recovery;
- issuer pause, address freeze, delayed redemption, and bank cutoff times;
- exchange and off-ramp outages, thin liquidity, and slippage;
- FX quotes, local payout failure, returns, refunds, and reconciliation;
- sanctions alerts, false positives, manual review, and customer redress;
- accounting, tax records, privacy controls, and data deletion;
- provider exit and migration to a replacement route.
Track success from instruction to usable recipient funds, not to a block explorer status. Useful measures include total cost, completion-time distribution, failure and manual-review rates, liquidity consumed, reconciliation exceptions, recovery time, and exposure by issuer, network, custodian, bank, and off-ramp.
What stablecoins actually change
Stablecoins can provide a common programmable asset on networks that operate beyond banking hours. They can make the token-transfer leg observable and composable with software. They may reduce some correspondent or prefunding frictions in a well-designed corridor.
They do not remove the need for trustworthy reserves, redemption, safe custody, legal clarity, liquidity, foreign exchange, compliance, operational resilience, and local money delivery. In many deployments, those dependencies move to new entities and interfaces rather than disappear.
The right comparison is not “blockchain versus banks.” It is one complete payment arrangement versus another, measured by who owes what, when the recipient can use the funds, what can fail, who can reverse or freeze an action, how much the full path costs, and how the system recovers under stress.